

Concora Credit

- 1.69K Reviews
- 3.4
- Downloads
- 1,000,000+
Our take on Concora Credit from Appgk
Managing a credit account is rarely difficult because of one dramatic task. The real trouble usually comes from small moments: remembering when to check a balance, finding the right payment details, confirming whether a recent action went through, or working out what to do when something looks unfamiliar. I spent time using Concora Credit with that everyday workflow in mind, and my impression is that it is most useful as a focused account-management tool rather than a complete personal finance system.
That distinction matters. This is a free finance app from Concora Credit, designed to help customers manage their account or accounts from a mobile device. It is available for Everyone, runs on devices using Android 7.1 or later, and has reached over one million installs. Its average rating sits at 3.4 from around three thousand five hundred ratings, with roughly one thousand seven hundred written reviews. Those figures suggest a service many people rely on, but also one that has produced a mixed experience for a noticeable group of users.
I would recommend approaching it as a practical doorway into your Concora Credit relationship. It can reduce the need to use a browser or search through old messages, especially when you want to check account information during a busy day. At the same time, it is not the app I would choose for building a full budget, comparing several lenders, tracking every household bill, or replacing broader money-management software.
From a payment question to a clear account check
The starting condition: what problem the app actually solves
The best reason to install this app is simple: you already have a Concora Credit account and want a direct way to manage it. Imagine getting home after work and realizing you are not sure whether a payment was processed, or checking your available account information before making another purchase. Opening a dedicated account app is more purposeful than navigating a general banking application and hoping the relevant details are easy to find.
Best Parts of Concora Credit
Things to Keep in Mind About Concora Credit
That focused purpose is also the app’s main limitation. It is not presented as a neutral financial dashboard that gathers accounts from different providers. If your goal is to see a checking account, savings account, cards, loans, and investments in one place, a conventional banking app or a multi-account finance tracker will usually be more suitable. Concora Credit keeps the journey centered on its own account relationship, which is helpful when that is exactly what you need and restrictive when it is not.
Before relying on it for an urgent task, I would make the first session a setup session rather than waiting until a payment deadline. Install it while you have your account information available, sign in carefully, and take a moment to learn where the main account actions are located. That small preparation makes a difference because a finance app is most valuable when it is already ready before a stressful situation appears.
News and Features Related to Concora Credit

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The first step: getting from installation to account access
The app is free, so the initial decision is straightforward. After installation, the important handoff is between the phone and your Concora Credit account. This is where I would slow down and verify that I am using the correct credentials and the correct account context, particularly if I manage more than one account. A mistake at this stage can make a simple task feel like an app failure when the real issue is account selection or sign-in information.
Once access is established, I would not immediately start changing anything. My preferred workflow is to inspect the account overview first, identify the balance-related information, and then locate the area used for payments or other account actions. This gives me a mental map of the app. It also helps separate information I am only reviewing from actions that may have consequences.
Don't want to read the full review?
That separation is one of the more useful habits with a finance app. I treat the opening screen as a place to gather facts, not as an invitation to tap through quickly. If I need to make a payment, I confirm the account and amount before moving forward. If I am checking a transaction, I compare the displayed information with my own records instead of assuming that the first screen tells the entire story.
Moving through the account: a repeatable routine
For regular use, I found the most sensible routine is short and deliberate. I open the app, check the relevant account information, review recent activity when I need context, and then decide whether an action is necessary. If a payment is due, I move into the payment process only after confirming that I am working on the intended account. If nothing needs attention, I close the app rather than exploring unrelated screens.
Screenshots
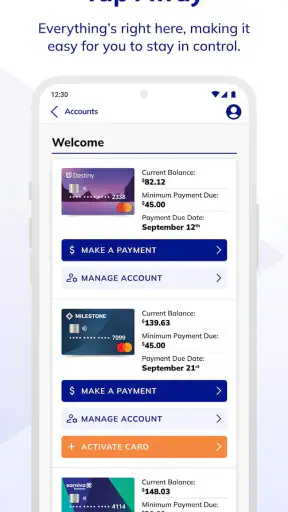
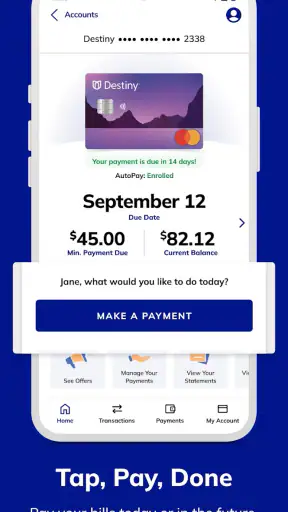
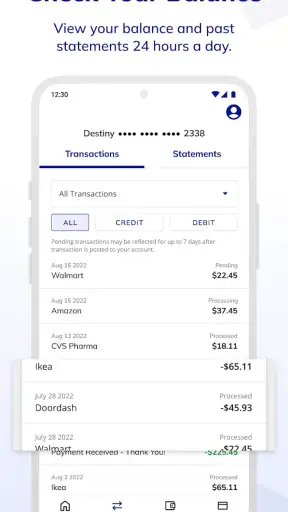
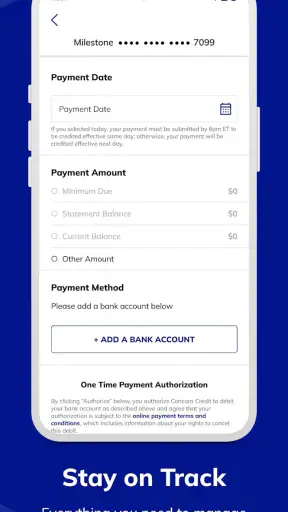
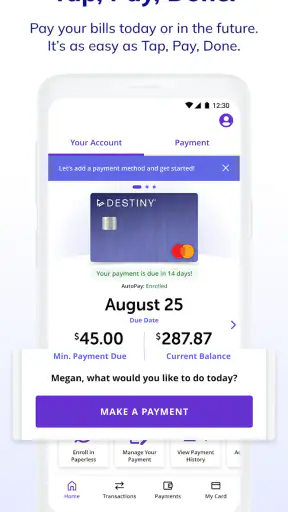
This may sound obvious, but it is a meaningful trade-off. A narrow app can be easier to use because it does not bury the account task under budgeting charts, investment news, or unrelated offers. The same narrowness means it will not help you answer a broader question such as, “How much can I safely spend across all my obligations this month?” For that, I would keep a separate budget or banking tool beside it.
A useful non-obvious tip is to use the app as a confirmation checkpoint rather than as your only financial record. After completing an important action, I would save the confirmation details in whatever personal record-keeping method I already trust. The app can be the place where I initiate or inspect the account activity, while a calendar, spreadsheet, or household finance routine can preserve the bigger picture.
Handoffs that deserve extra attention
Every account task involves handoffs: from you to the app, from the app to the account service, and sometimes from the account information back to your own records. The smoothest part is usually the first one, because the app gives you a dedicated route into the Concora Credit account. The less comfortable part is knowing exactly when a displayed status represents a completed result, a pending step, or information that still needs verification.
My advice is not to close the process mentally just because a button has been pressed. Read the final screen, look for a confirmation or updated account state, and keep a note of what you intended to do. If the balance or activity view does not change immediately, avoid repeating the same action impulsively. Duplicate attempts are precisely the kind of mistake that can happen when a user confuses a slow update with a failed request.
This is also where the app’s mixed rating becomes relevant. A 3.4 average is not a reason to dismiss it, but it is a reminder that finance apps are judged during high-pressure moments. A user who opens the app for a calm balance check may have a very different experience from someone trying to resolve a sign-in problem or confirm an urgent payment. I would keep an alternative support route available for situations the app cannot settle on its own.
Handling more than one account
The store summary specifically describes managing account or accounts, so users with multiple Concora Credit relationships should think about organization from the beginning. The key practical question is not simply whether several accounts can be viewed, but whether you can confidently tell which account you are viewing before taking action. I would make that check part of every payment workflow rather than relying on memory.
A simple personal system helps: record a short identifying note for each account in your own secure records, then compare it with the account context shown in the app before continuing. Do not use a shared or exposed note for sensitive credentials. The point is to prevent the common human error of selecting the familiar-looking account instead of the intended one.
This workflow is particularly useful for households where one person handles several accounts but another person needs to understand what happened. The app manages the service-side interaction; your shared household record handles the communication handoff. That division keeps the app from being forced into a role it was not designed to fill.
What the result looks like in everyday life
Consider a realistic Saturday morning. I want to review my Concora Credit account before planning the week’s spending. I open the app, identify the account, inspect the current information, and review recent activity if something looks different from my own notes. If a payment is needed, I follow the account action flow and check the resulting status before leaving. I then update my personal budget record so the payment is included in the wider household picture.
The outcome is not a complete financial plan. It is a reliable answer to a narrower question: what is happening with this Concora Credit account right now, and what action do I need to take? For that purpose, a dedicated app is more convenient than repeatedly finding the service through a mobile browser. It also creates a repeatable habit, which is often more useful than a long list of advanced features that I never open.
Another practical use is preparing for a customer-service conversation. Before contacting support about an unfamiliar transaction or account detail, I would check the app first, note what is displayed, and gather the relevant context. That can make the handoff clearer because I am describing a specific account state rather than saying only that “something looks wrong.” The app does not replace support, but it can help me approach support with better information.
Where the workflow breaks
The first weak point is scope. If you expect a full financial command center, this app will feel limited. It is centered on Concora Credit account management, so it does not take the place of a general banking app, a bill organizer, or a budgeting platform. I would skip it as a primary finance app if my main need is to combine information from many institutions.
The second weak point is that account management depends on successful access and clear confirmation. A mobile interface can make routine actions convenient, but it cannot remove the consequences of entering the wrong information, choosing the wrong account, or failing to verify the final status. I would never treat a quick tap as proof that a financial task is complete.
The third is expectation management. Because the app is free and focused, some users may expect it to provide the depth of a paid budgeting product or the broad services of a full bank application. That is not the right comparison. Its fair comparison is the mobile browser route to the same account, and in that comparison the dedicated format can be more convenient for repeat checks. Against a feature-rich finance hub, it naturally offers less breadth.
There is also a human support boundary. When the issue involves account access, a disputed transaction, identity questions, or a result that does not match your records, I would stop repeating taps and move to the appropriate Concora Credit support process. The app is useful evidence and an access point, but it should not encourage you to troubleshoot a serious account problem indefinitely on your own.
Who should install it, and who should choose something else
I think this app is a good fit for an existing Concora Credit customer who wants a convenient mobile route for checking and managing an account. It is especially practical for someone who checks account information while away from a computer, handles more than one Concora Credit account, or wants a dedicated place for this relationship instead of mixing it with everyday banking.
I would be more cautious if you are looking for financial education, spending categorization, long-term planning, or a unified view of your entire financial life. In those cases, a banking app with broader account aggregation or a dedicated budgeting tool would serve you better. You can still keep Concora Credit installed for account-specific tasks, but it should not be expected to become the center of your whole money system.
Privacy and device habits also matter. Since this is a finance app, I would use a phone protected by a screen lock, avoid signing in on a shared device, and take care when reviewing account information in public. Those are not special features of the app; they are sensible precautions whenever a mobile tool provides access to financial details.
My conclusion after following the full workflow
Concora Credit succeeds when the job begins and ends with a Concora Credit account. Its value is practical: open the app, identify the account, inspect the information, complete an appropriate action, verify the result, and carry the outcome into your own financial records. That focused path is easier to repeat than a browser-based routine, particularly for customers who want quick access during ordinary daily situations.
Its limitations are just as clear. It is not a replacement for a complete budgeting system, a multi-bank dashboard, or direct human assistance when an account problem becomes complicated. The mixed public rating reinforces my advice to use it carefully during important transactions: verify the account, read the final status, and keep a separate record for payments or other consequential actions.
The app was released on June 21, 2023, and its current version is 3.0.17. Those details are useful when checking that your installation is reasonably current, especially if the interface you see differs from instructions elsewhere. Overall, I would install it if I had a Concora Credit account and wanted a free, dedicated management tool. I would simply keep my expectations narrow and my verification habits strong. Used that way, it is a convenient account companion rather than an all-purpose financial solution.
Concora Credit FAQ
What is Concora Credit, and how does it work?
Concora Credit is a financial service associated with credit products offered through participating retail partners. After applying, eligible users may receive a credit account that can be used according to the terms provided by the lender. The app or online account area generally helps customers review balances, payment activity, statements, and account details. Approval, credit limits, interest rates, and available features depend on individual eligibility and the specific account agreement.
Is Concora Credit a loan app or a credit card app?
Concora Credit is primarily connected with retail credit accounts rather than functioning like a general-purpose cash loan application. Depending on the retailer and offer, the account may be used to finance purchases or manage a store-related credit line. Before applying, users should carefully check the lender’s disclosures, annual percentage rate, fees, minimum payments, and where the account can be used, since terms may vary between offers.
Can I apply for Concora Credit directly from the app?
The application process may begin through a participating retailer, promotional offer, or Concora Credit account page, depending on the product available in your region. You will normally need to provide personal and financial information for identity verification and credit assessment. Applying does not guarantee approval, and a credit inquiry may affect your credit profile. Read all consent notices and terms before submitting an application.
Are there fees or interest charges with Concora Credit?
Concora Credit accounts may include interest charges, late-payment consequences, or other costs described in the account agreement. Some promotional financing offers can appear attractive, but they may have specific conditions, such as requiring payments by certain dates or applying deferred interest if the balance is not paid in time. Always review the fee schedule, APR, payment due date, and promotional terms before making a purchase.
Is Concora Credit safe to use, and how can I protect my account?
Concora Credit should be accessed only through its official app, verified website, or a trusted retailer link to reduce the risk of phishing and fraudulent pages. Use a strong, unique password, enable available security features, and avoid entering account details on public or shared devices. Regularly review statements and transaction history, and contact official customer support immediately if you notice unauthorized activity or suspicious communications.











